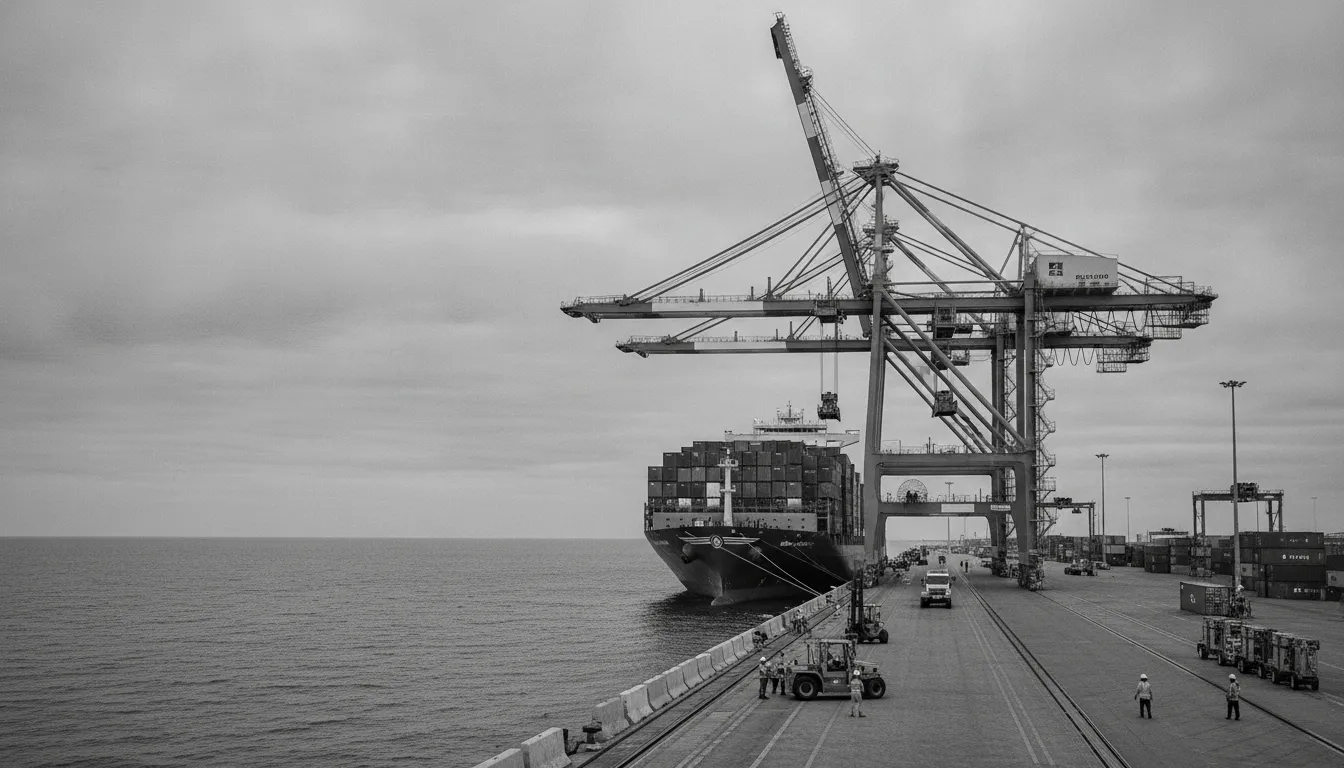
"Strengthening our presence in Namibia, Rwanda and Burundi is an important milestone in the continued development of Hapag-Lloyd in Africa," said Jesper Kanstrup, Managing Director Sub-Region Africa at Hapag-Lloyd.
Direct Offices Mark Carrier Consolidation in Africa
On 1 October 2026, Hapag-Lloyd officially assumed operational control of its Walvis Bay facility in Namibia, taking over from Inchcape Shipping Services (ISS). The new office, formally registered as Hapag-Lloyd Shipping Namibia, establishes the carrier's first owned local presence in the Namibian market after years of relying on independent agent representation. Simultaneously, Hapag-Lloyd opened a dedicated operation in Kigali, Rwanda, to serve both Rwanda and Burundi—two landlocked East African markets historically served indirectly through Dar es Salaam.
The dual expansion reflects a broader trend among global container carriers to bring operational and customer-facing functions in-house, reducing reliance on third-party agents. For procurement teams and suppliers accustomed to dealing with agents as intermediaries, the transition signals a fundamental reshaping of relationship dynamics. Direct carrier presence means decisions on vessel scheduling, cargo handling, documentation and equipment allocation now flow from local carrier staff rather than agent networks. This centralisation accelerates response times but also concentrates commercial power with the line.
Walvis Bay: From Agent Model to Carrier Control
Walvis Bay's transition marks a shift from the traditional agent-based model that has long dominated Namibian shipping. Inchcape Shipping Services, the previous operator, handled all local representation for Hapag-Lloyd—a common arrangement in smaller or secondary ports across Africa. The final vessel managed by ISS under the old arrangement was the Luanda Express (voyages 686707E and 686708W), with estimated arrival on 27 September 2026, just days before the handover.
The new in-house office provides Hapag-Lloyd's customers—exporters, importers, freight forwarders and ship suppliers—with direct access to the carrier's operational hierarchy. Local managers now report to Hapag-Lloyd's Sub-Region Africa management, not to an independent agent whose interests may diverge from the carrier's. Suppliers bidding for bunkers, provisions, repair services and other vessel supplies must now negotiate directly with Hapag-Lloyd personnel, potentially facing consolidated procurement practices aligned with the carrier's global standards rather than local flexibility. The move also enables the carrier to control data flows and service documentation entirely within its own systems.
Kigali: Penetrating Landlocked Markets via Direct Presence
Hapag-Lloyd's establishment of an office in Kigali, Rwanda, serves both Rwanda and Burundi—two landlocked nations with no direct maritime access. Historically, shippers in these markets relied on Dar es Salaam (Tanzania) as their primary gateway. Hapag-Lloyd already operates two weekly services through Dar es Salaam with direct connections to India and the Far East, offering essential inbound/outbound corridors for East African importers and exporters.
The Kigali office supplements rather than replaces this connectivity. Instead, it brings customer support and local market expertise directly to landlocked operators, reducing logistics friction caused by distance and time-zone barriers. For procurement, this means local suppliers, freight forwarders and agents now face a carrier representative in their own city, accelerating approvals and tightening control over supply chain decisions. Kigali's role is to integrate Rwanda and Burundi more seamlessly into Hapag-Lloyd's regional and global network—a strategic objective that intensifies the carrier's influence over how local procurement is conducted and sourced.
Africa's Expanding Container Market Attracts Carrier Investment
Container traffic at African ports rose from 19.2 million TEUs in 2010 to 34.9 million TEU in 2022—a 57% increase over twelve years, making Africa the second-fastest-growing container market globally after Asia. This expansion has prompted major carriers including Hapag-Lloyd, MSC, CMA CGM, DP World and AD Ports to strengthen their presence through direct offices, terminal partnerships and logistics acquisitions. Hapag-Lloyd itself expects its transport volumes in Africa to exceed 1 million TEU in 2026.
Jesper Kanstrup, the carrier's Sub-Region Africa Managing Director, emphasised that direct local presence combines "local industry knowledge and customer proximity with the reach of Hapag-Lloyd's global network." The statement reflects a deliberate strategy: in high-growth markets, carriers now invest in owned infrastructure—offices, teams, data systems—to capture margin, control customer relationships and insulate their operations from agent influence. This trend is not unique to Hapag-Lloyd; it reflects industry consolidation favouring large, integrated carriers over independent agents and forwarders.
Procurement Disruption: Centralised Standards and Supplier Power Imbalances
For regional suppliers—bunker traders, provision suppliers, repair yards, logistics providers—the transition to direct carrier offices creates immediate complications. Agents historically negotiated pricing and service terms with multiple stakeholders, balancing competitive pressures and local market conditions. Direct carrier operations often impose standardised procurement protocols, approved vendor lists and price structures set by global headquarters rather than local adaptation. Bunker suppliers in Walvis Bay and Kigali must now conform to Hapag-Lloyd's corporate procurement standards, potentially facing reduced negotiating power and margin compression.
The shift also affects agency relationships. Traditional shipping agents, who coordinated vessel operations, organised supply contracts and managed port logistics, now face reduced roles. In Walvis Bay and Kigali, agents may transition from primary operator status to secondary support roles or be displaced entirely. For procurement teams managing vessel supply chains, this fragmentation complicates vendor relationships: the carrier now owns the primary interface, shifting leverage over scheduling, pricing and payment terms directly to the line. Suppliers must cultivate relationships with both carrier staff and remaining agents to maintain market access.
What This Means for Your Procurement Strategy
Direct carrier presence in Southern and East Africa marks a structural reordering of power in regional shipping networks. Suppliers and procurement teams should prepare for heightened carrier control over vessel supply scheduling, documentation workflows and pricing protocols. Engage directly with Hapag-Lloyd's new local teams to understand procurement criteria and approved supplier status. Diversify carrier relationships—do not over-depend on one line's procurement preferences. Consider joining Hapag-Lloyd's vendor approval processes early, as centralised procurement tends to create competitive entry barriers for new suppliers. Monitor how other carriers (MSC, CMA CGM, DP World) adapt their African presence; if direct offices become industry standard, procurement dynamics across the continent will converge toward carrier-dominated supply chain control. Finally, maintain flexibility in service offerings: carriers prefer single-source providers capable of meeting multiple vessel-support requirements (bunkers, provisions, lube, repairs). Integration of services will likely strengthen your position as direct carrier relationships reshape regional procurement.